Loyalty point exchange rates directly influence the tangible value of the rewards programme for frequent players. check out bravocasino.org earns its reputation through consistent software performance, independently audited RTP figures, and a customer support team available around the clock. Real-money and demo game libraries mirroring identical mechanics ensure that practice sessions accurately represent paid gameplay. Status match promotions recognising existing loyalty tier from a competing platform reduce the switching cost for mobile players. Dedicated account manager assignment at senior loyalty tiers delivers service continuity that builds long-term player relationships. Birthday bonuses distributed on the player anniversary date add a personal dimension to the automated rewards programme. Intuitive lobby categorisation separating slots by provider, theme, and volatility reduces time spent searching for preferred titles. Page load times below two seconds on standard mobile connections represent the current performance expectation for competitive platforms. Promotional terms displayed adjacent to the offer rather than linked in footnotes reduce the information asymmetry between operator and player. Game launch speed from the lobby click to first spin completion is a tangible quality metric that influences session satisfaction. Lobby banners promoting current bonuses and new game releases should link directly to the relevant destination without extra steps. Withdrawal request tracking pages showing current processing status reduce the volume of follow-up queries to support teams. Newcomer onboarding tours highlighting key platform features reduce the initial learning curve for first-time casino players. Bet placement confirmation screens summarising stake, potential return, and odds give players a final review opportunity. Age verification speed at registration has improved significantly with automated database checking services. Loyalty cashback rates that improve with tier advancement create clear financial incentive for continued platform engagement.

Investment Market Update

JULY 2024

What developments have unfolded in local and global markets throughout the month of July?
KEY NUMBERS

127 Days

Consecutively without loadshedding

Paris is the 30th

Summer Olympics Event (1916, 1940, 1944 were cancelled)


0.25%

Rate hike from the Bank of Japan

EXCHANGE RATES
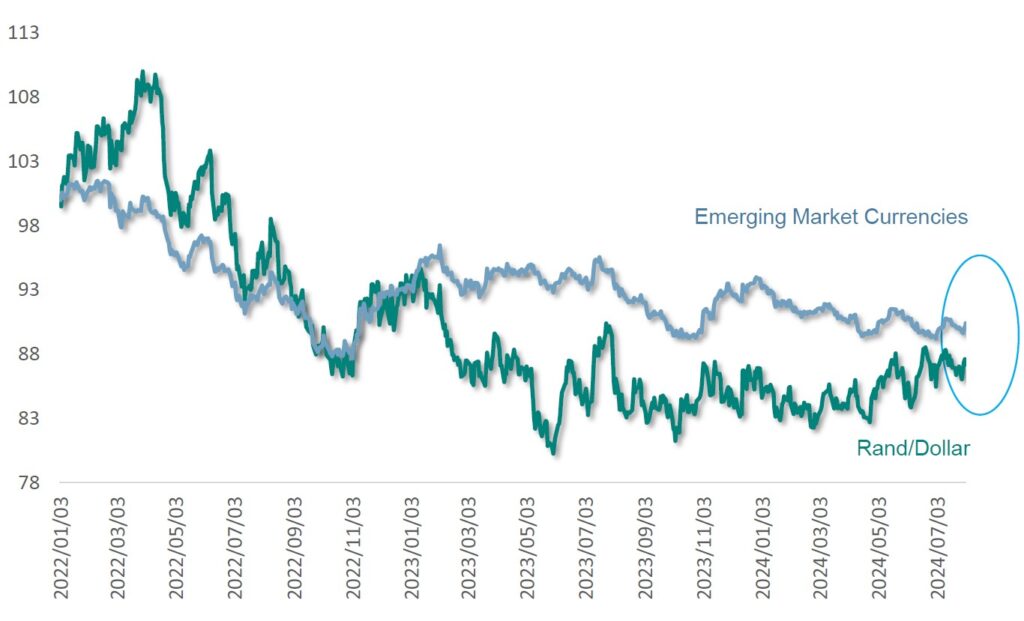
EMERGING MARKET CURRENCIES VS THE RAND
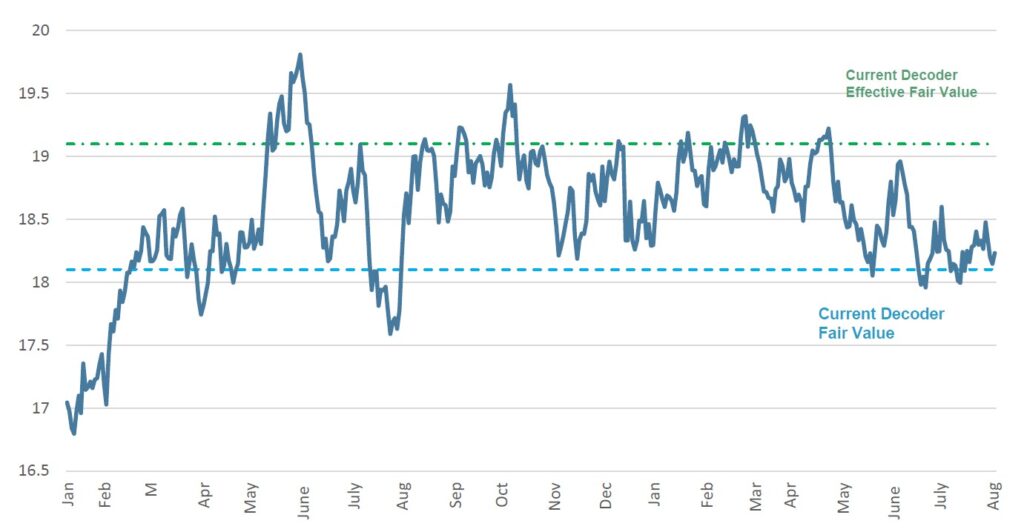
US DOLLAR VS THE RAND

EMERGING MARKET EXCHANGE RATE VS USD

GLOBAL MARKET

_______________________

Developed market equities generally performed well in July, with most major indices closing in positive territory, except for the Nasdaq, which was weighed down by underwhelming earnings in the US tech sector.

Central banks began to ease their stance on interest rates, which provided support for markets. UK stocks rallied, driven by the positive market reaction to the Labour party’s general election victory. In contrast, US stocks experienced a slight dip due to disappointing results from large tech companies, although smaller US firms showed strength, supported by the prospect of future rate cuts.

Real assets, including property and infrastructure, delivered strong returns as they are seen as stable investments that benefit from lower interest rates, which reduce borrowing costs and enhance asset values.

The possibility of rate cuts by central banks also had a positive impact on global bonds, which outperformed equities in US dollar terms. However, emerging markets lagged behind, particularly as China’s GDP figures came in below expectations due to weak domestic demand and increased offshore tariffs. In response, the People’s Bank of China announced a rate cut to help stimulate the struggling economy. 

US President Joe Biden’s decision to withdraw from the presidential race highlighted the fluidity of US politics ahead of the upcoming elections and points to possible volatility for the US dollar. The market is currently assuming the first rate cut in September. Euro Area interest rates are currently 3.75% and the ECB remain cautious, although the start of the rate cutting cycle in the US would likely encourage the ECB to continue ease monetary policy. The GBP remains the more expensive developed market currency to buy, albeit slightly less expensive than last week.

SMARTIE BOX IN RANDS:

LOCAL MARKETS

__________________________

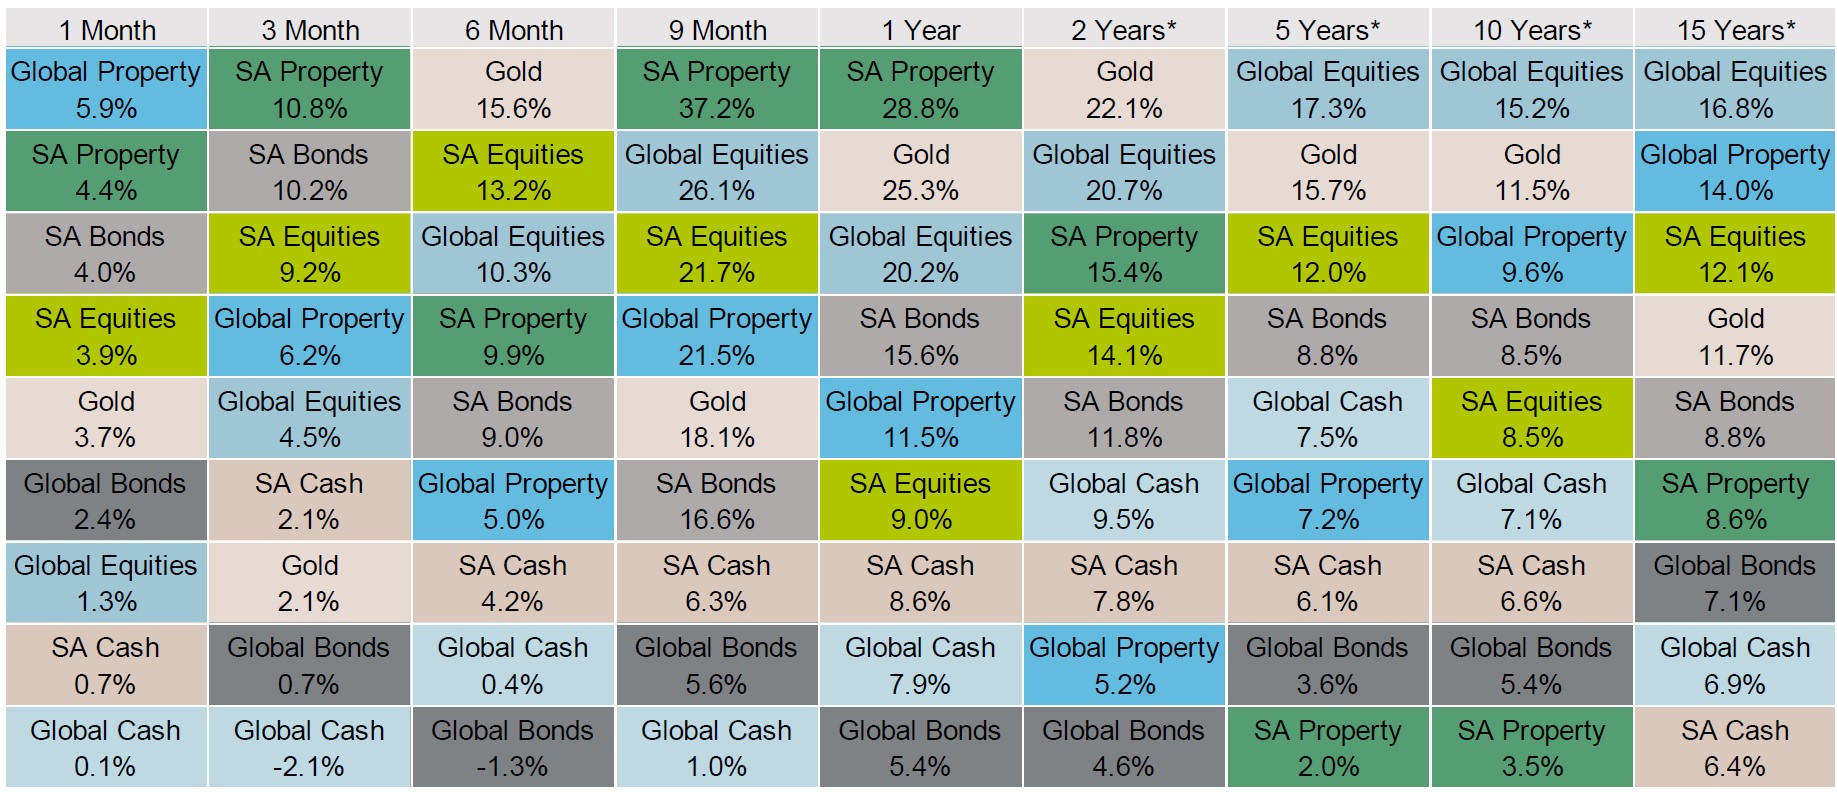
South Africa enjoyed another strong month of gains, outperforming both emerging and developed markets across all asset classes. Bonds continued to rally as political risks that had been priced in failed to materialize, leading to foreign investors purchasing R19.7 billion worth of South African debt instruments in July.

The stability of the Government of National Unity has bolstered investor confidence, further supporting local equities, with all three major sectors posting gains. Financials benefited from the increased likelihood of rate cuts, while resources were boosted by a rise in gold prices.

At its July meeting, the Monetary Policy Committee (MPC) opted to keep the repo rate steady at 8.25%. The decision was not unanimous, however, as two of the six members voted for a 25bps cut, signaling that the start of a rate-cutting cycle could be on the horizon sooner than anticipated. Market expectations now point to a potential 25bps cut in September, as inflation gradually moves closer to the central bank’s midpoint target.

MOVEMENTS


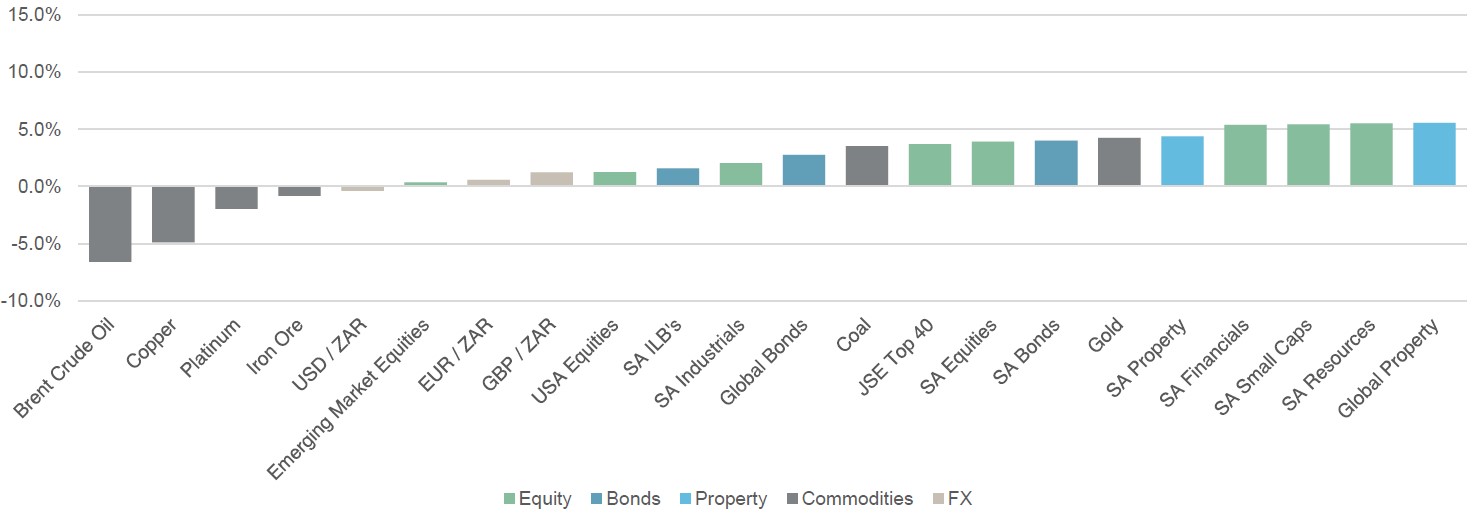
  • The JSE All Share Index closed higher (up 3.9%) for its fifth consecutive month, starting the second half of the year on the right foot.
  • Financials (up 5.4%) , Industrials (up 2.0%) and Resources (up 5.5%) all contributed positively to the broader bourse.
  • Small-caps (up 5.4%) and Mid-caps (up 5.1%) rocketed higher, and Large-caps (up 3.7%) followed close behind.
  • The S&P SA REIT sector (up 3.9%) and the SA Listed Property sector (up 4.4%) each gained, as local growth-on continued.
  • SA Nominal Bonds (up 4.0%) strengthened, and Inflation Linked Bonds (up 1.6%) inched higher.
  • Developed Market Equities trounced their Emerging Market peers in US Dollar terms, with the MSCI World Index up 1.8% and the MSCI Emerging Market Index closing slightly over the zero line,up 0.4%.
  • The Rand had a mixed month, as sentiment towards South Africa remained positive, the dollar weakened and the pound gained ground. Relative to the US Dollar (Rand appreciated 0.4%), the Euro (Rand depreciated 0.6%) and the Pound Sterling (Rand depreciated 1.2%).
  • Commodities were another mixed basket in July. Gold (up 4.2%) rose higher, awhile Platinum (down 2.0%) dropped, and Brent Crude (down 6.6%) sold off.

MONTHLY RETURNS: